
Wide-ranging operator MTY Group this past quarter concluded a strategic review that began a year ago in November. At the outset, it included, among a bevy of options, the potential sale of all or part of the company. That won’t happen, MTY Group announced Friday during its Q3 review, as a special committee of independent directors and the board elected to “accelerate the evolution of MTY’s current strategic plan, with a sharpened focus on efficiency, simplification, and disciplined capital allocation.”
However, this doesn’t mean MTY, which directs Kahala Brands and its 28-plus concepts (like Cold Stone, Blimpie, Pinkberry, and Wetzel’s), as well as BBQ Holdings (Famous Dave’s, Village Inn, and nine others), and Papa Muphy’s, alongside a host of Canadian concepts such as Mr. Sub and Thai Express (the company is based north of the border), isn’t looking at its portfolio.
CEO Eric Lefebvre told investors “everything is for sale if the price is right.”
“But there’s no strong desire to divest of good brands,” he explained. “… Every brand will need to be evaluated for its potential and for the plan we have to make it grow. And the brands we might decide … are no longer relevant might not necessarily be the underperforming brands.”
It could, Lefebvre added, be concepts MTY doesn’t have plans for or can’t come up with value creation. “But yes,” he said, “I would expect that more underperforming brands will be discussed than the top brands that are performing well.”
MORE: Papa Murphy’s to Close Up to 50 Restaurants
At Q3’s close, MTY’s fleet covered 6,966 locations, of which 6,782 were franchised or under operator agreements and 184 corporate. Fifty-seven percent were housed in the U.S.; 35 percent in Canada; and 8 percent international.
The company opened 72 stores and closed 146. Fifty shuttered locations were related to a corporate closure announcement made last quarter. Company-run restaurants now comprise 2.6 percent of MTY’s network versus 3.6 percent a year ago—an effort it’s continuing.
Additionally, 27 new stores slated for Q3 pushed into Q4 thanks to “various uncontrollable delays.”
Regarding the company-run closure note, Lefebvre said, he expects the bulk of one-time costs to reflect over the coming two quarters, with benefits from stripping underperforming units surfacing the ensuing period, including an estimated $2.5 million benefit.
The company identified seven more restaurants it expects to go dark on top of 68 it guided previously to bring the total to 75. As shared, 50 have already closed.
Most were repossessed stores (restaurants MTY bought from franchisees hoping to improve) and a few stemming from acquisitions over recent years.
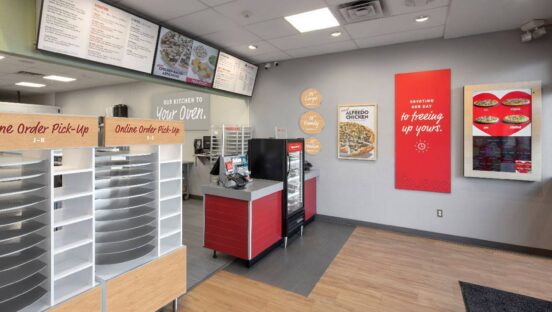
For instance, a Papa Murphy’s portfolio MTY took over two years ago. Eventually, the company came to the realization those stores weren’t going to reroute. Simply, some regions were more damaged than anticipated.
“The rationalization of corporate stores marks an important step for the company in our pursuit of value creation, growth and taking decisive action,” Lefebvre said.
MTY’s Q3 system sales were essentially steady, year-over-year, at $1.5 billion and same-store sales decreased 1.9 percent. Canada was flat; the U.S. slid 2.7 percent; and international dropped 9.1 percent.
Lefebvre said MTY’s strategic review, initiated November 17, 2025, resulted in conversations with a “range of interested parties” and the company considered a broad set of options. It generated interest among potential investors and reaffirmed, he said, the “strength, resilience, and strategic value of MTY’s platform.”
Part of optimizing the company’s suite of brands will be to keep reverting to an asset-light franchising model. In recent years, MTY worked on bolstering company-run stores so it could sell strong-performing units to operators while it closed lagging ones. The goal being to get back to being a pure-play franchisor like it once was with, perhaps, 1 percent of restaurants being corporate. Lefebvre said getting there will simplify operations.
“While mergers and acquisitions are part of MTY’s DNA,” Lefebvre said, “the board of directors believes the best opportunity available today is MTY itself. Few acquisition targets offer the value and quality that MTY does.”
Lefebvre said there’s added emphasis amid changes to evaluate each brand and try to realize its potential. And if that means it would perform better with a different owner, MTY could take action. “… one thing for sure is that we want to go back to growth in general, which is something that we’ve been lacking,” he said. “We had a really good period following COVID. The years, ’22, ’23 were very strong, and we’ve been declining last year and this year.”
Again, Lefebvre reiterated, the plan isn’t to sell “the crown jewels.”
Refranchising isn’t a “fire sale process.”
“We’re not going to give the stores away,” he said. “… we’ll find good franchisees to put the stores in good hands where it can perform and make sure that our network is healthy.”
Lefebvre added it will take time as MTY systematically approaches refranchising with the right valuation for stores. But wheels are turning. The first two Sauce Pizza and Wine locations—previously fully corporate—were recently dealt to operators.
Overall, Lefebvre said, attrition of brands happens naturally every year. There might be four, five, or six concepts that disappear for MTY where it converts them into stronger brands.
In other terms, the company’s overall number of brands tends to tick down naturally.
Yet for other concepts where it has franchise agreements, MTY has a duty to operators, he said, to do its best and try to help make it work, whether through marketing or other assistance. MTY can’t terminate a brand unilaterally and decide it wants to stop operating it.
“We just need to respect our commitments to our franchisees that are in these franchisee agreements,” Lefebvre said.
That review is going to keep happening—which brands are slated for natural extinction, and which might be worth having someone else run them.
“Some underperforming brands might have a bright future, and we’ve turned around a number of brands in the past,” he said. “So, if we have a plan and if we think that we can do better than we’re doing now, we’re probably going to retain these brands. But there are brands out there that maybe would be more valuable in somebody else’s hands. And we’re going to have to review that carefully. And I have nothing to announce at the moment in terms of which brands that would represent, but it’s certainly review that’s happening.”
“We love all our brands,” Lefebvre added later on the call. “We want them to do well. We want all our franchisees to do well. And if we’re going to sell a brand, it’s going to be for the right value and also for the right buyer. So, I don’t want to commit to a timeline. Obviously, time is of the essence, and it’s not something that we want to agonize over forever. So, you should see some action probably in ’27.”
Lefebvre said the U.S. consumer has been a bit more volatile and unpredictable than Canada. The vast majority of MTY’s brands “had a rough” Q3 and even top concepts “suffered to a certain extent.”
He said the company is trying to ensure its offers are relevant in today’s environment as much as possible.
One callout was Papa Murphy’s, where Lefebvre said high-performing franchisees “are doing extremely well.”
“The business model and the economic model and the margins we drive with Papa Murphy’s are really good,” he said. “And that helps even when sales are going down slightly, the stores remain profitable. But there are some pockets of where it’s a little bit more challenging, where sales need a serious lift for franchisees to be able to turn a good healthy profit and deliver on their return on investment expectations. So it’s a challenge, but I will say that the business model for Papa Murphy’s allows for a little bit more sales variations because the margins are still healthy.